

For decades, companies have built their supply chains around efficiency, buying where prices are lowest and delivering products just in time. But the world has changed, bringing with it new rules and opportunities for trade, as business leaders rethink how to keep goods moving through disruption.
“We made one mistake when we began to treat efficiency as if it were the same thing as security,” said Kristupas Vaitiekūnas, Vice-Minister of Foreign Affairs, Republic of Lithuania. “We assumed trade would always flow, that contracts would always be honored, and that interdependencies would keep conflicts at bay." Those assumptions have since been challenged, Vaitiekūnas noted.
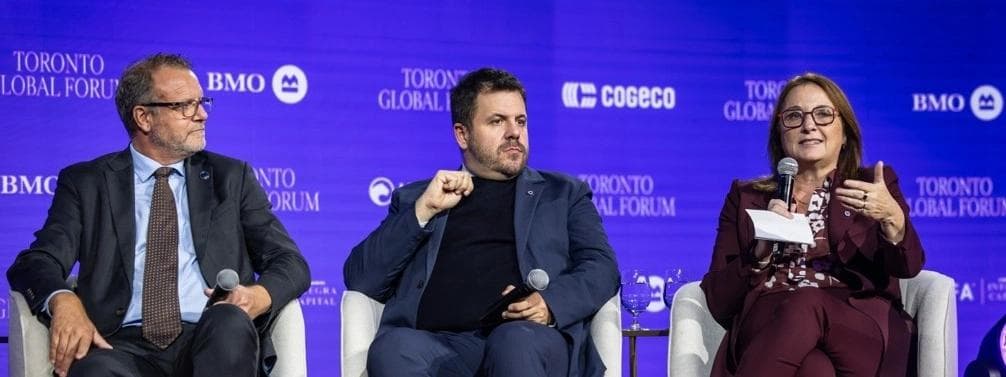
His opening remarks set the stage for the “Navigating Resilient Supply Chains in an Era of Global Disruption” panel at the 20th annual Toronto Global Forum, organized by the International Economic Forum of the Americas (IEFA). The discussion focused on how businesses can prepare for shocks while continuing to grow, and how infrastructure investment and government policy can support those efforts. It featured:

Sharon Haward-Laird, Group Head, Canadian Commercial Banking & North American Integrated Solutions, and Co-Head, Canadian Personal & Business Banking, BMO Financial Group
Rob Ritchie, Executive Vice President, Food and Industrial Ingredients U.S./Canada & LATAM and Sugar Reduction, Ingredion
Roelof-Jan (RJ) Steenstra, President & CEO, Toronto Port Authority
Julien Baudry, Vice President, Strategic Affairs and Communications, Port of Montréal
Amir Atri, Vice President, Western, Central and Atlantic Canada, GardaWorld Security Canada
Martha Harrison, Partner, Co-Head, International Trade & Investment Law, McCarthy Tétrault (moderator)
Build resilience into growth plans
Recent global disruptions have exposed the risks of relying too heavily on a single supplier, country or market. From energy to critical raw materials and production, greater concentration can leave supply chains vulnerable to geopolitical and economic pressure.
Among Canadian businesses, understanding those vulnerabilities is increasingly part of future planning. Sharon Haward-Laird said the BMO clients she’s spoken with are building resilience into strategy design, rather than treating it as disaster planning. She noted that supply chain management has become a much more prominent C-suite consideration amid recent global disruptions. “Now it's sometimes a dealbreaker,” she said.
That’s one reason global ingredients supplier Ingredion uses a regional manufacturing network. Rather than relying on one large plant to supply customers worldwide, the company operates multiple facilities across the regions it serves, explained Rob Ritchie. That gives the company flexibility to adjust its supply chain and activate contingency plans when trade shocks or transportation problems interrupt the movement of goods.
Build the connections to support diversification
As Canadian businesses look to diversify their trade, Martha Harrison said they should be mindful of introducing new risks to their supply chains. Amir Atri agreed, noting that while adding suppliers and routes can strengthen resilience, diversification also requires organizations to consider the new risks and dependencies that may come with a more complex supply chain. Canada can’t control what happens abroad, but it can work to make it easier to move goods within its borders. Julien Baudry said businesses need confidence that Canada’s ports, rail lines and trade corridors can handle the growing volume of trade with markets beyond the U.S., underscoring the importance of keeping infrastructure investment aligned with the country’s trade ambitions.
RJ Steenstra pointed to Canada’s strong transportation infrastructure as a foundation for greater resilience and flexibility. More closely connecting trade routes across the country, including making greater use of the Great Lakes, could give businesses more options to move goods and adapt when disruptions occur.
Baudry encouraged Canadian businesses to reconsider assumptions about distance and international trade costs, noting that, depending on route and transportation options, shipping goods overseas is not always more expensive than moving them long distances overland within North America.
Turn investment plans into action
Haward-Laird explained how financial institutions can help businesses fund the necessary changes while managing uncertainty. Some clients are seeking financial flexibility and assessing which investments to delay, while others want help managing exposure to commodity prices, interest rates and currencies.
Greater certainty around project approvals can make it easier for businesses to plan long-term investments and secure financing. Government guarantees and other programs can further support investment by sharing risk, while banks bring capital and execution expertise.
“That’s where I think we can see the magic happen in Canada,” she said.